
 +965 2292 4888


Daily Economic Update
02.11.2026
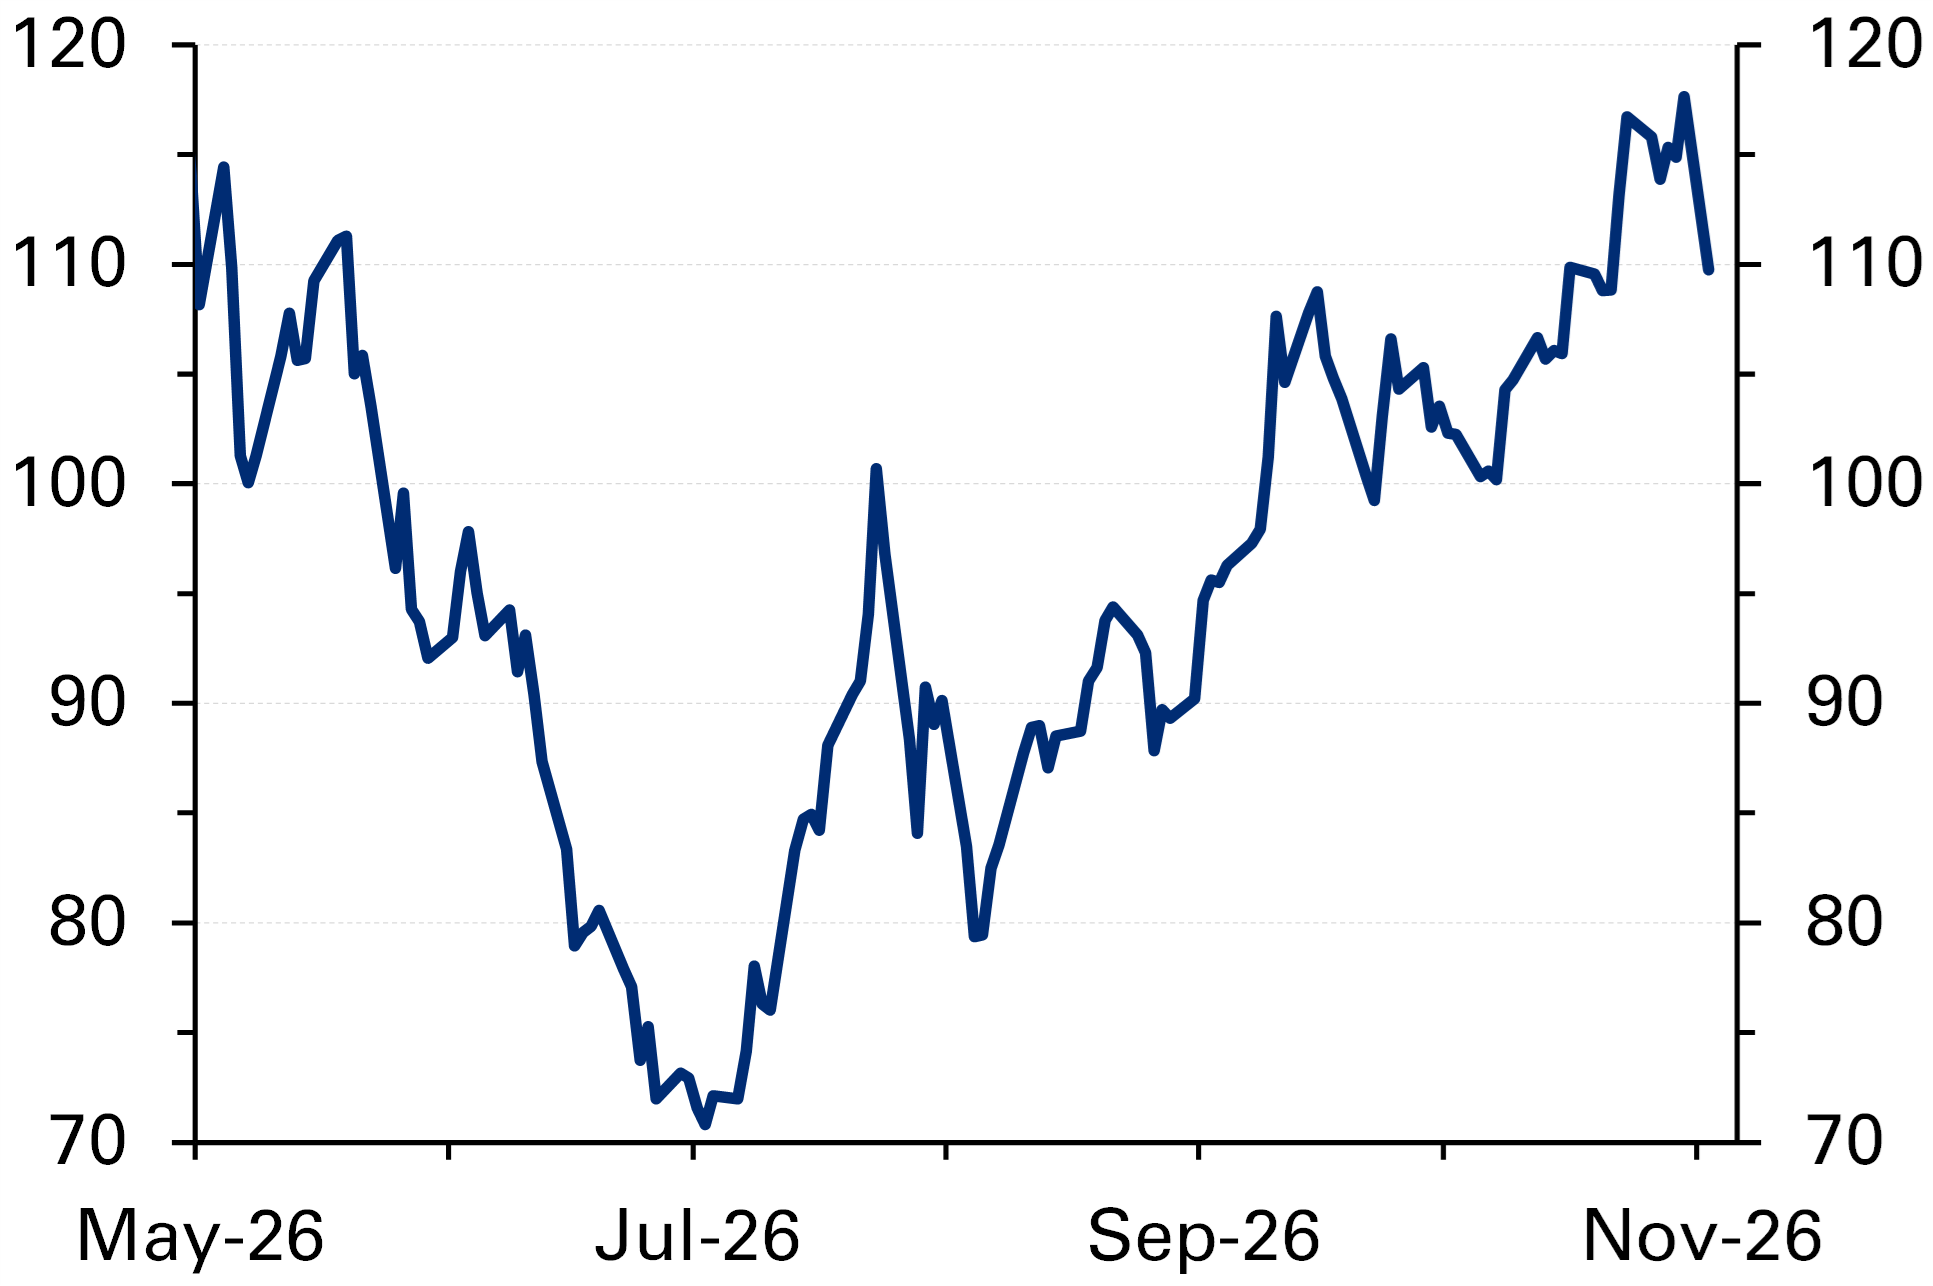
Oil: Prices retreat in early Asian trading as Trump gestures towards more diplomacy. Brent futures (January contract) were paring back gains in early trading this morning, falling more than 3% to under $110/bbl at the time of writing, following reports over the weekend that President Trump is inclined to give diplomacy more time amid a more concerted push by GCC officials, especially the Qataris, to work towards some settlement with their Iranian counterparts. The Qatari effort has seen officials shuttling backwards and forwards to Tehran. The Iranians proposed opening the Strait of Hormuz within two rather than the earlier five days if the US met its conditions including lifting its blockade of Iranian ports. Last week saw Brent settle at a six-month high of $117.6/bbl, following a rise of 2% on Friday, and record a fourth consecutive weekly gain. Sentiment remained dominated by geopolitical developments, with markets increasingly pricing in the risk of renewed US military action against Iran following this Tuesday’s US midterm elections. Indeed, Brent ended October up 13.6% m/m, a second consecutive month of double-digit gains, supported by growing speculation surrounding President Trump's proposed restart of the "Epic Fury" campaign, continued attacks on shipping in the Strait of Hormuz—the most recent over the weekend when a Qatari LNG tanker was struck attempting to transit the Strait—and persistent Houthi strikes on Saudi energy infrastructure including the attack on Ras Tanura’s refinery last week. Qatar and Pakistan have remained actively engaged in mediation efforts, and the US, through Vice President JD Vance, has also reached out to the Iranians about a possible framework for direct negotiations, potentially hosted in Qatar or Turkey. Such an agreement would pave the way for renewed negotiations on a broader settlement. Discussions between Qatari and Iranian officials reportedly continued in Doha on Saturday, highlighting that diplomatic channels remain active even as markets continue to assign a high probability of further escalation. Meanwhile, OPEC+ met yesterday to discuss output policy for December, but there were no surprises as members kept output targets unchanged for the month. The disruptions in the Gulf have meant that most members are continuing to produce below their quotas.
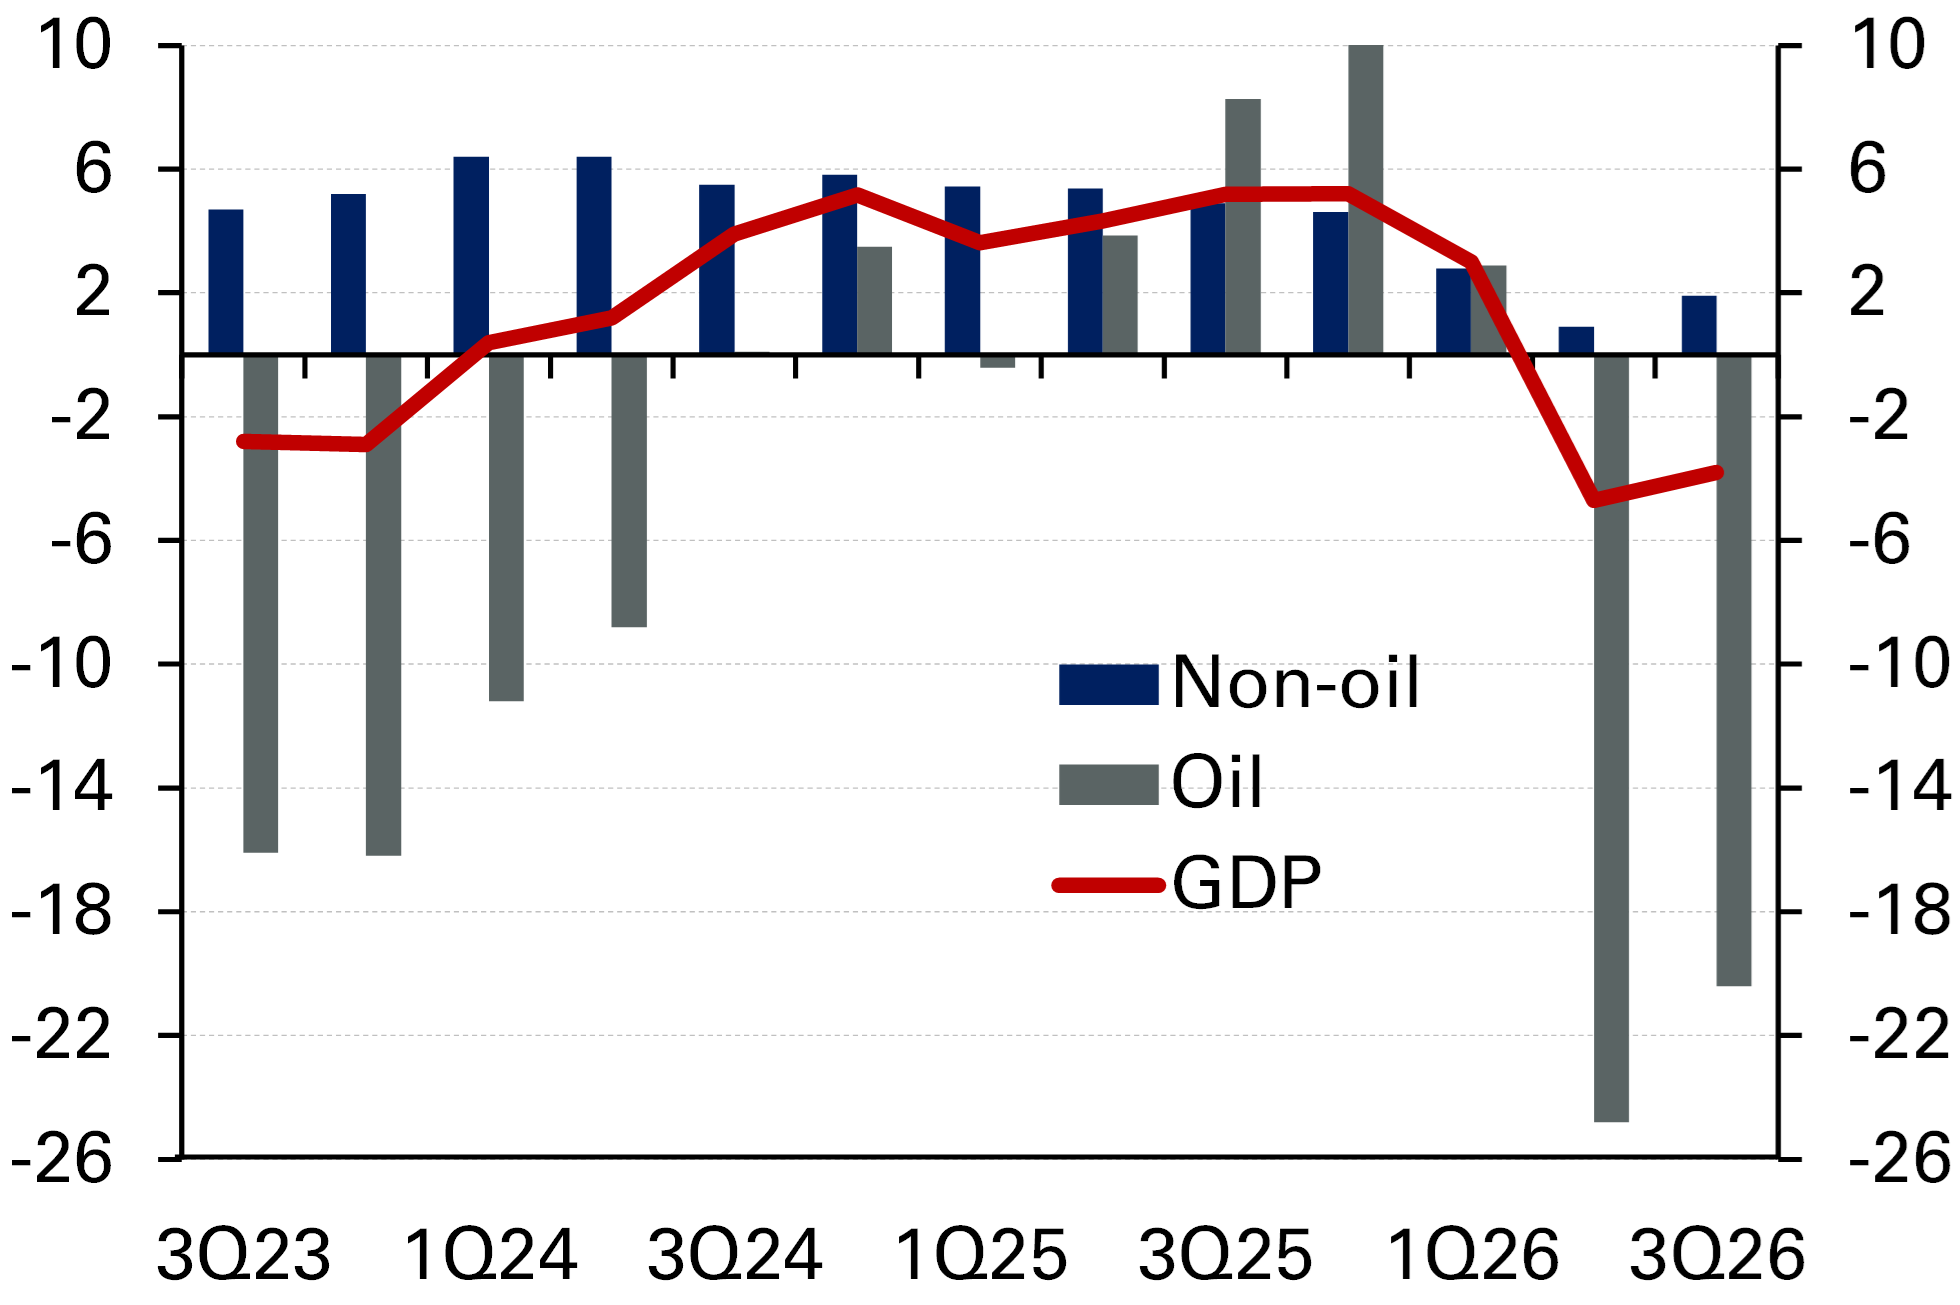
Saudi Arabia: Oil slump drives GDP contraction despite non-oil growth. Saudi Arabia’s economy contracted by 3.8% y/y in Q3 2026, as a sharp decline in oil activity more than offset continued growth in the non-oil sector, according to GASTAT. Oil activity fell by 20.4% y/y, while non-oil activity expanded by 1.9%. The annual contraction reflects the impact of the eight-month US-Iran conflict, which disrupted shipping through the Strait of Hormuz and weighed on oil production and exports. Houthi attacks on airports and energy facilities also added to the disruption. However, quarterly figures point to some recovery. Seasonally adjusted GDP grew 1.3% q/q in Q3, supported by a 5.7% rebound in oil activity, while non-oil activity increased by a more modest 0.6%. Government activity was the only major component to contract, declining by 1.2% q/q. Saudi Arabia has partly mitigated the disruption to oil shipments by rerouting crude through its East-West pipeline to Red Sea ports. Overall, the figures suggest that the oil sector remains the main constraint on economic performance, while non-oil activity continues to provide some support to growth.
Egypt: Government secures US$1bn World Bank financing linked to economic reforms. The government signed a $1 bn development policy financing agreement with the World Bank, according to a Cabinet statement. This is the second tranche of a three-phase program launched in June 2024. The second phase of the program is linked to reforms aimed at improving the governance of state-owned companies, reducing barriers to private investment, strengthening competition, increasing government revenues, and improving the financial sustainability of the electricity and water sectors. The Bank had approved the financing in May, comprising $800 mn from the Bank and a $200 mn UK-backed credit guarantee. The funds will be disbursed directly to the state budget once the required reforms are legislated. The third and final phase, expected next year, will focus on attracting more private investment into key sectors.
Global: US mid-term elections, October jobs report, and BoE meeting key matters this week. In the US, the congressional mid-term elections are on Tuesday, and the expectation is that Democrats will take control of the House from Republicans. The Democrats winning majority in the Senate is a harder feat, but that is also possible. Several Fed officials will speak over the week, likely explaining their thought process behind the FOMC’s rate decision last week, and hopefully shedding light on their thinking for the December FOMC meeting. Attention will also be on the Treasury’s quarterly refunding announcement (today and on Wednesday) as rising UST bond yields pressure government finances. The October jobs report is due on Friday, and consensus forecasts point to a 65K increase in non-farm payrolls along with a steady unemployment rate of 4.2%. Street projections also signal a slightly higher ISM manufacturing PMI (today) reading of 54.7 in October (54.5 in September) but a marginally lower services gauge (Wednesday) of 54.8 (54.9 in September). In the Eurozone, flash inflation for October is due on Wednesday, with headline CPI expected to rise 3.9% y/y in October (3.8% in September), but the core rate seen steady at 2.5%. On Friday, retail sales are expected to show a 0.1% m/m contraction in September, reversing a 0.1% increase in August. In the UK, the Bank of England’s policy decision is due on Thursday, with a 25bps rate hike near certain (around 98% probability). The Bank will also release updated macroeconomic projections. Finally in Japan, employees’ cash earnings for September is due on Friday, with consensus expectations at +3.8% y/y, unchanged from August.